
Pull to refresh
Logo
Blackstone agrees to buy about 16% of India's IIFL Finance

Blackstone agrees to buy about 16% of India's IIFL Finance

Money Moves

The $535 million cheque is part of a ₹6,414 crore raise that lifts IIFL's capital adequacy ratio from 17% to roughly 30%

Overview

Updated 47 minutes ago

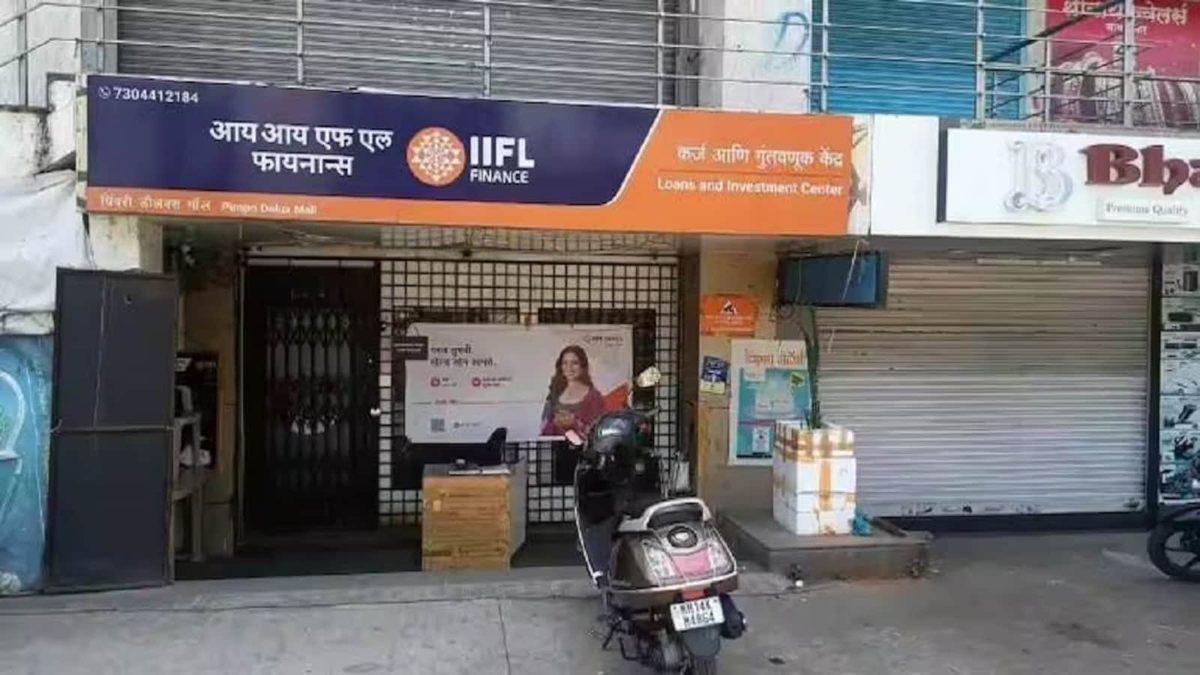
IIFL Finance lends against gold and to small businesses from more than 5,000 branches across India. On November 10 its board approved a ₹6,414 crore capital raise, with Blackstone paying ₹5,000 crore, about $535 million, for a 15.57% fully diluted stake.

The money is aimed at the constraint that sets what an Indian non-bank lender pays to borrow. IIFL's capital adequacy ratio rises from 17% to roughly 30%, net gearing falls from 4.6 times equity to 2.8, and management puts each 25 basis points saved on funding at about ₹200 crore a year.

Why it matters

Cheaper funding for one lender is a pricing signal for all of them: foreign equity is now underwriting Indian retail credit.

Questions about this story

Free account needed to ask — your question is kept and asked for you right after sign-up. Answers are public.

No questions yet — be the first to ask.

Key Indicators

$683 million
Total capital raise
Preference shares and promoter warrants approved by the board on November 10.
$535 million
Blackstone's investment
Roughly ₹5,000 crore, routed through an affiliate called Ingot SG Pte Ltd.
15.57%
Blackstone's fully diluted stake
Assumes conversion of the preference shares and exercise of the warrants.
30%
Pro forma capital adequacy ratio
Up from about 17% before the raise, on a September 2026 basis.
₹1.24 trillion
Assets under management
Consolidated, as of September 30, 2026; up 38% year on year.
1.5%
Gross non-performing assets
Share of total loans, down 7 basis points in three months.
2.8x
Net gearing after the raise
Down from 4.6 times equity, according to the managing director.

Voices

Curated perspectives — historical figures and your fellow readers.

Sign up to generate historical perspectives on this story.

People Involved

Organizations Involved

Timeline

September 2026 December 2026

5 events Latest: Today
Tap a bar to jump to that date
  1. Shareholders scheduled to vote at extraordinary general meeting

    Upcoming Scheduled

    The EGM will also consider amendments to the articles of association and Blackstone's special rights.

  2. Board approves ₹6,414 crore preferential issue

    Today Board approval

    Blackstone's Ingot SG Pte Ltd takes ₹5,000 crore of preference shares at ₹602 each; promoters add ₹1,264 crore of warrants.

  3. Blackstone wins board seats and consent rights

    Today Deal terms

    Two non-executive directors while it holds about 10% or more, plus reserved-matter consent and pre-emptive rights. No change of control.

  4. Managing director frames the deal as a funding-cost fix

    Today Statement

    Nirmal Jain says capital adequacy reaches about 30%, gearing falls to 2.8x, and a rating upgrade could follow.

  5. Talks between IIFL and Blackstone surface

    Deal talks

    CNBC-TV18 reports that the two sides are in discussions over a minority stake in the lender.

Scenarios

1

Shareholders approve, and Blackstone's money lands by March

Likely Resolves by Q1 2027

Discussed by: IIFL Finance management and the deal filings, which treat the EGM as the main remaining gate

The resolution passes on December 4 with promoter support and institutional votes, the company files the allotment, and the preference shares start their 18-month clock to conversion. The capital shows up in the December-quarter balance sheet, gearing falls, and IIFL resumes lending at its gold-loan pace of ₹2,000–3,000 crore a month.

2

A rating agency upgrades IIFL within a year

Possible Resolves by Q3 2027

Discussed by: Nirmal Jain, who says the fundamentals now support an upgrade and that agencies make the call

Higher tier-1 capital, gearing near 2.8x and a 90% secured book are the inputs rating agencies weigh. An upgrade of one notch would cut wholesale funding costs across the book, which management values at roughly ₹200 crore a year per 25 basis points. Rating agencies move on their own timetable and often wait for a full year of post-deal performance.

3

The capital sits idle and returns fall below the 16% target

Unlikely Resolves by Q2 2027

Discussed by: Analysts who cover Indian non-bank lenders and watch return on equity against cost of capital

If loan growth does not absorb the new equity quickly, the extra capital dilutes return on equity instead of lowering funding costs. Management argues there is no negative carry because the cash either repays debt or goes out as gold loans within weeks. A weak quarter of disbursements would test that claim.

4

Another foreign firm buys into an Indian lender

Possible Resolves by Q2 2027

Discussed by: Reuters, which lists five recent or proposed foreign purchases of stakes in Indian banks and non-bank lenders

Blackstone's deal sits inside a run of foreign money entering Indian credit: Canada's Fairfax Financial proposed buying 60.72% of IDBI Bank, Bank of America agreed to buy 49.9% of Jio Financial Services' lending arm, Japan's MUFG invested in Shriram Finance, and Emirates NBD agreed to buy 60% of RBL Bank. A large equity cheque is the cheapest way into a market where building a branch network from scratch takes years.

Historical Context

2 moments from history that rhyme with this story — and how they unfolded.

September 2018

IL&FS default and India's non-bank credit squeeze (2018)

Infrastructure Leasing & Financial Services, a large infrastructure financier, missed payments on short-term debt in September 2018. Banks and mutual funds that had been lending to non-bank lenders pulled back across the sector, and wholesale funding seized up for companies with no relationship to IL&FS.

Then

Several lenders failed or were restructured, including Dewan Housing Finance in 2019.

Now

Credit ratings and asset quality became the gatekeepers of funding. Lenders that could not show a secured book and adequate capital paid more to borrow, or could not borrow at all.

Why this matters now

IIFL's raise is aimed at exactly that gap. Management ties the new equity to a possible rating upgrade and cheaper borrowings, not to faster loan growth for its own sake.

March 2020

Reserve Bank of India rescues Yes Bank (2020)

The Reserve Bank of India took control of Yes Bank in March 2020 after a run on deposits. State Bank of India led a group of banks that recapitalised it, and holders of the bank's additional tier-1 bonds had their investments written off.

Then

Depositors were protected and the bank reopened under new management, with existing shareholders heavily diluted.

Now

The episode fixed the hierarchy of Indian lender capital in investors' minds: equity and tier-1 buffers decide whether a lender needs a state rescue to survive a shock.

Why this matters now

IIFL is raising equity while it is healthy, taking capital adequacy to about 30%. That buffer is what separates an independent lender from a rescued one.

Sources

(7)