
Pull to refresh
Logo
SEC proposes scaling back executive pay disclosure rules

SEC proposes scaling back executive pay disclosure rules

Rule Changes

Fewer named executives, a higher perk threshold and simpler tables

Overview

Updated 43 minutes ago

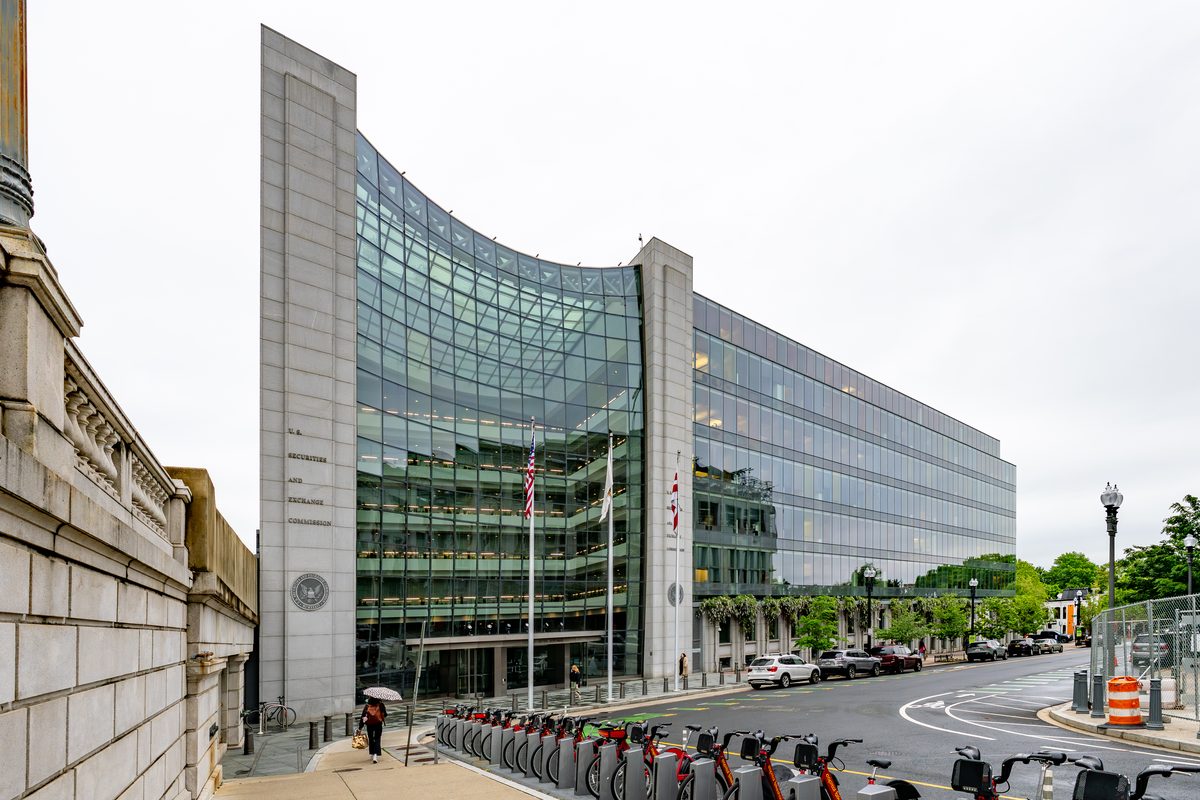
The Securities and Exchange Commission (SEC) proposed on November 13, 2026, to shrink the executive pay disclosures public companies file each year. In most cases, companies would report detailed pay for two executives instead of five, and would not have to itemize perks worth less than $150,000.

The proposal is the first comprehensive rewrite of the SEC's executive compensation rules since 2006. It would replace four pay tables with three, simplify the pay-versus-performance and CEO pay ratio calculations, and give companies more room to decide what counts as a perk. Investor groups say the changes would reduce what shareholders can learn about how executives are paid.

Why it matters

If adopted, shareholders would see pay details for two executives instead of five, and perks under $150,000 would stay off the table.

Questions about this story

Free account needed to ask — your question is kept and asked for you right after sign-up. Answers are public.

No questions yet — be the first to ask.

Key Indicators

2
Named executive officers under proposal
Down from five or more in most cases.
$150,000
Perquisite reporting threshold
Up from $10,000, with a new de minimis tracking exclusion.
3
Compensation tables
Replacing the four tables required today.
$1.64B
Estimated annual savings
SEC estimate across all registrants, about $244,000 each.
60
Comment period in days
Starts when the proposal is published in the Federal Register.
5 years
Pay ratio determination frequency
Proposal would require it every five years, limited to U.S. full-time employees.

Voices

Curated perspectives — historical figures and your fellow readers.

Sign up to generate historical perspectives on this story.

People Involved

Organizations Involved

Timeline

July 2006 November 2026

6 events Latest: Yesterday
Tap a bar to jump to that date
  1. SEC proposes scaling back Item 402

    Latest Rulemaking

    Would cut named executives to two, raise the perk threshold to $150,000 and simplify tables.

  2. SEC holds executive compensation roundtable

    Hearing

    Gathered companies, investors and advisers; drew more than 80 comment letters.

  3. SEC adopts pay-versus-performance rule

    Rulemaking

    Required tables linking executive pay to company performance.

  4. SEC adopts CEO pay ratio rule

    Rulemaking

    Companies had to compare chief executive pay with median employee pay.

  5. Dodd-Frank mandates new pay disclosures

    Legislation

    Law required say-on-pay votes, a CEO pay ratio, pay-versus-performance tables and clawback policies.

  6. SEC rewrites executive pay disclosure rules

    Rulemaking

    Item 402 overhaul added the Compensation Discussion and Analysis, new tables and expanded perk disclosure.

Scenarios

1

SEC adopts the proposal largely as written

Likely Resolves by End of 2027

Discussed by: SEC Chairman Paul Atkins and the agency's proposing release

The 60-day comment period closes, the SEC reviews feedback, and the commission votes out a final rule that keeps the two-officer standard and the $150,000 perk threshold. Companies would apply it starting the first full fiscal year after the effective date.

2

Comment pressure forces the SEC to soften the rule

Possible Resolves by End of 2027

Discussed by: Better Markets, Public Citizen and investor comment letters

Investor groups and some lawmakers push back, and the final rule keeps five named executives, a lower perk threshold, or both. The SEC could also re-propose parts of the rule rather than adopt it whole.

3

Proposal stalls without a final rule

Unlikely Resolves by End of 2027

Discussed by: Skeptics who note the 60-day comment period and a crowded SEC agenda

The proposal draws heavy opposition, the SEC's agenda shifts, and no final rule reaches a vote by the end of 2027. The existing Item 402 rules stay in place.

Historical Context

3 moments from history that rhyme with this story — and how they unfolded.

July 2006

SEC executive compensation overhaul (2006)

The SEC adopted its biggest rewrite of executive pay rules in decades, requiring a Compensation Discussion and Analysis, new tables and detailed perk disclosure. It applied to fiscal years ending on or after December 15, 2006.

Then

Companies added CD&A sections and expanded footnotes to proxy statements.

Now

The framework lasted two decades and became the baseline the 2026 proposal would replace.

Why this matters now

The current proposal is the first comprehensive rewrite since, and it targets the complexity the 2006 rules created.

July 2010

Dodd-Frank pay disclosure mandates (2010)

After the financial crisis, Congress required say-on-pay votes, a CEO-to-median-worker pay ratio, pay-versus-performance tables and clawback policies. The SEC spent years writing rules for each.

Then

The pay ratio rule arrived in 2015 and the pay-versus-performance rule in 2022.

Now

The mandates became fixtures of proxy statements and targets for complaints about compliance cost.

Why this matters now

The 2026 proposal would simplify the pay ratio and pay-versus-performance rules while saying it still meets the statutory mandates.

August 2015

CEO pay ratio rule (2015)

The SEC adopted a rule requiring companies to disclose the ratio of CEO pay to median employee pay, as Dodd-Frank required. Companies had to identify a median employee and calculate the ratio.

Then

The rule took effect for fiscal years beginning on or after January 1, 2017, with first disclosures in 2018.

Now

It became one of the most criticized disclosures for cost and comparability.

Why this matters now

The proposal would limit the median-employee population to U.S. full-time workers and require the calculation every five years.

Sources

(9)