Cost Accounting Standards created (1970)
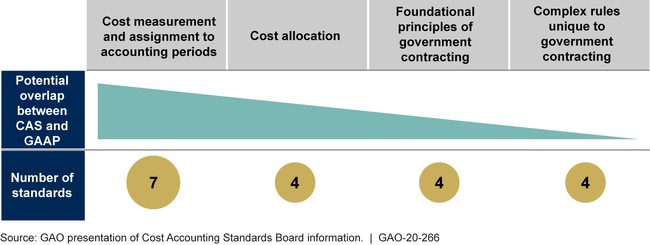
Congress passed Public Law 91-379 creating the Cost Accounting Standards Board to standardize how defense contractors allocate costs, after Vietnam-era cost overruns exposed wide variations in accounting practices. The first standards took effect in 1972, requiring Disclosure Statements and compliance for contractors above set dollar thresholds.
Defense contractors faced uniform cost accounting rules, with full compliance required on larger awards.
The framework governed federal cost accounting for over five decades, with thresholds rising periodically but the core structure remaining intact.
The 1970 law built the regulatory apparatus the 2026 rule now dismantles at the margins. Today's changes preserve the framework's core while raising entry points dramatically.