Pull to refresh
Logo
Grab agrees to buy 60% of Atome Financial for $1.49 billion

Grab agrees to buy 60% of Atome Financial for $1.49 billion

Money Moves

Ride-hailing and delivery giant deepens its push into consumer lending across Southeast Asia

Yesterday: Grab's raised growth targets tied to Atome deal go public

Overview

Updated 1 hour ago

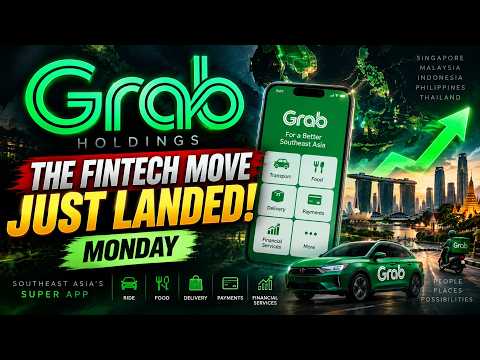
Grab, Southeast Asia's largest ride-hailing and delivery company, agreed on September 15 to buy 60% of consumer lender Atome Financial for $1.49 billion in cash. Completion is expected by the third quarter of 2027, pending regulatory approval across the five markets where Atome operates.

Atome runs buy-now-pay-later loans, consumer cash loans, BNPL cards, and digital lending in Singapore, Malaysia, the Philippines, Indonesia, and Thailand. It has 25 million cumulative users and a $1 billion gross loan portfolio. Grab says the merged financial services segment targets $500 million in adjusted EBITDA by 2028 on a combined loan book above $6 billion.

Why it matters

Grab is betting it can turn 54 million monthly users into lending customers — a test of whether Southeast Asia's super-apps can make consumer credit pay.

Questions about this story

Free account needed to ask — your question is kept and asked for you right after sign-up. Answers are public.

No questions yet — be the first to ask.

Key Indicators

$1.49 billion
Cash paid for 60% stake
Upfront price for a controlling interest in Atome Financial.
60%
Controlling stake acquired
Grab's initial equity interest in Atome Financial.
$4.5 billion
Phase 2 valuation cap
Maximum valuation for the remaining 40% stake, floored at $2 billion and tied to adjusted EBITDA and revenue.
25 million
Atome cumulative users
Transacted users across five Southeast Asian markets.
$6 billion
Target loan book by 2028
Combined gross loan portfolio Grab expects by 2028.
$1.7 billion
Raised 2028 group EBITDA target
Up from $1.5 billion, alongside revenue growth of over 30% annually from 2025 to 2028.

Voices

Curated perspectives — historical figures and your fellow readers.

Ever wondered what historical figures would say about today's headlines?

Sign up to generate historical perspectives on this story.

People Involved

Organizations Involved

Timeline

September 2025 September 2026

4 events Latest: Yesterday
Tap a bar to jump to that date
  1. Grab's raised growth targets tied to Atome deal go public

    Latest Announcement

    Grab's revised outlook — over 30% annual revenue growth from 2025–2028 and a $1.7 billion 2028 group EBITDA target — circulates as deal analysis spreads.

  2. Grab signs $1.49 billion deal for 60% of Atome Financial

    Acquisition

    Grab and Atome's parent AIGL sign definitive agreements. Completion expected Q3 2027. Grab raises 2028 targets: $500M segment EBITDA, $6B loan book, $1.7B group EBITDA.

  3. HSBC-led banks expand Atome facility to $345 million

    Funding

    An upsized syndicated credit facility led by HSBC gives Atome more capital to grow its loan book.

  4. Maya Bank lends Atome $48 million

    Funding

    Atome expands its Philippines credit capacity with a facility from Maya Bank, part of a broader push to fund loan book growth.

Scenarios

1

Regulators clear Grab-Atome deal; Phase 1 closes by Q3 2027

Likely Resolves by Q3 2027

Discussed by: Grab management, Reuters, CNBC

Grab wins merger approvals across Singapore, Malaysia, the Philippines, Indonesia, and Thailand. The Phase 1 purchase completes on schedule, Atome is consolidated into Grab's financial services segment, and the two companies begin cross-selling — extending flexible payment options to Grab's users while sending new traffic to Atome's network of over 30,000 brands.

2

Regulators impose conditions or delay the deal

Possible Resolves by End of 2027

Discussed by: Analysts at pvtIQ and PwC (via Business Times)

One or more market regulators raises concerns about consumer credit concentration, data privacy, or responsible lending in buy-now-pay-later products. Approval arrives with conditions — such as data-separation requirements or lending caps — or slips beyond the third quarter of 2027, pushing Phase 2 further out.

3

Combined lending business misses its 2028 financial targets

Possible Resolves by Feb 28, 2029

Discussed by: Ben Lim (pvtIQ), Inside Retail Asia

Integration costs, rising defaults, or slower cross-selling than expected keeps the financial services segment below the $500 million adjusted EBITDA target for 2028. The Phase 2 valuation for the remaining 40% would likely land near the $2 billion floor, limiting what AIGL and other sellers recover.

Historical Context

3 moments from history that rhyme with this story — and how they unfolded.

March 2018

Uber exits Southeast Asia to Grab (2018)

Uber sold its Southeast Asia ride-hailing and delivery operations to Grab in exchange for a 27.5% stake in the Singapore company. Grab bought market share and scale outright rather than outspending a well-funded rival.

Then

Grab became the dominant ride-hailing player across the region.

Now

It established Grab's pattern of acquiring scale in new businesses instead of growing them organically.

Why this matters now

The Atome purchase repeats that playbook in consumer lending: buying a proven operator rather than building the credit business internally.

August 2021 – January 2022

Square acquires Afterpay (2021)

Square agreed to buy Australian buy-now-pay-later firm Afterpay for $29 billion in stock. Afterpay's 16-million-customer loan book folded into Square's Cash App and merchant network, turning a standalone BNPL leader into a feature of a larger payments ecosystem.

Then

The deal closed in January 2022 and made BNPL the backbone of Block's consumer credit push.

Now

It became the template for payments companies absorbing BNPL lenders to gain consumer credit data and distribution.

Why this matters now

The Atome deal follows the same logic: Grab is absorbing a mature BNPL lender into its super-app instead of building consumer lending from scratch.

September 2021 – 2023

PayPal buys Paidy (2021)

PayPal paid $2.7 billion for Paidy, Japan's buy-now-pay-later leader, to expand in Japanese e-commerce credit. PayPal later folded Paidy into its broader merchant offerings rather than running it as a standalone BNPL brand.

Then

Paidy continued operating largely independently after the deal.

Now

The integration showed that absorbing a local lender into a large platform does not guarantee lending growth.

Why this matters now

It is a cautionary example for Grab: integrating a lender at scale carries execution risk even when the acquisition logic is sound.

Sources

(9)