
Pull to refresh
Logo
Canada launches real-time payments system without its biggest banks

Canada launches real-time payments system without its biggest banks

New Capabilities

Eight institutions can now clear and settle payments instantly, 24/7. The Big Six join later.

Overview

Updated 1 hour ago

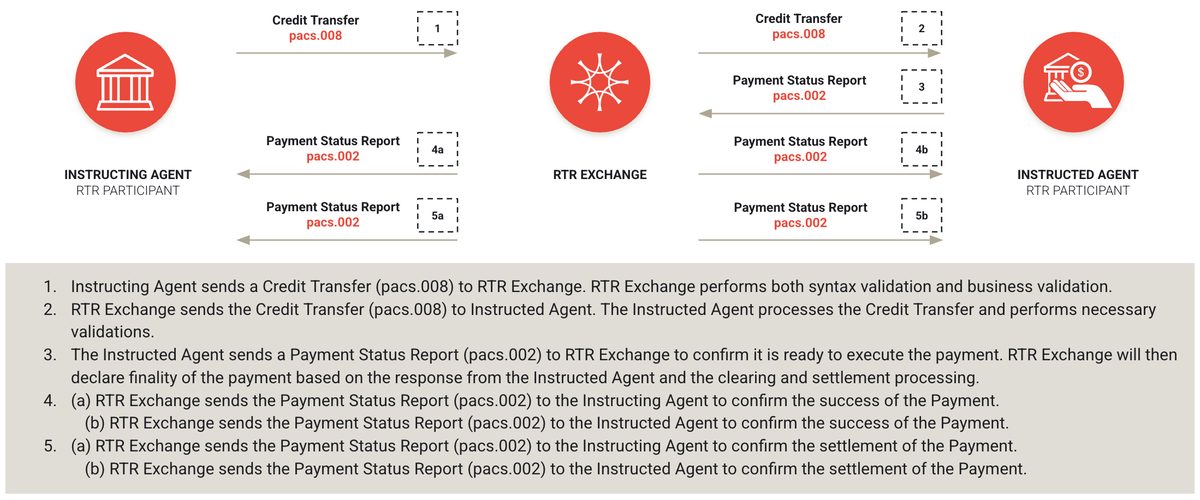
On November 9, customers of eight Canadian financial institutions gained the ability to send money that arrives in seconds, at any hour, any day of the year. Payments Canada switched on the Real-Time Rail (RTR), a national system that clears and settles payments instantly instead of over hours or days.

The first group of participants includes fintechs Wealthsimple and KOHO, plus Bank of America and several smaller institutions. None of Canada's Big Six banks, which hold about 93% of the country's banking assets, are on it yet.

Why it matters

Instant payments only work if the recipient's bank is connected. With the Big Six absent, most Canadians won't notice a change yet.

Questions about this story

Free account needed to ask — your question is kept and asked for you right after sign-up. Answers are public.

No questions yet — be the first to ask.

Key Indicators

8
Launch participants
Financial institutions able to clear and settle payments on the RTR at launch.
93%
Big Six share of banking assets
The share of Canadian banking assets held by the six largest banks, none of which are on the RTR at launch.
C$14.5B
Projected decade cost savings
C.D. Howe Institute estimate of savings from lower processing costs, less cash and cheque use, and reduced float.
9 in 10
Coverage target within first year
Payments Canada's goal for Canadian bank accounts reachable through the RTR.

Voices

Curated perspectives — historical figures and your fellow readers.

Sign up to generate historical perspectives on this story.

People Involved

Organizations Involved

Timeline

2015 November 2026

5 events Latest: Today
Tap a bar to jump to that date
  1. RTR goes live with eight participants

    Today Launch

    Payments Canada switches on the system; no Big Six bank is in the first group.

  2. Federal budget confirms launch date

    Policy

    The federal budget tabled that week officially announces the RTR launch.

  3. Launch rescheduled, then missed again

    Delay

    The target moves to 2022, then to mid-2023, then to 2026.

  4. Original launch target missed

    Delay

    The RTR fails to launch on its first scheduled date.

  5. RTR begins as a modernization project

    Origin

    Payments Canada starts work on a real-time payment system as part of a broader payments modernization effort.

Scenarios

1

Big Six banks go live on RTR by Q3 2027

Likely Resolves by Q3 2027

Discussed by: Payments Canada, Canadian Bankers Association

Payments Canada's launch timeline has all initial-phase participants at full transaction volumes by the third quarter of 2027. The Big Six have not announced individual go-live dates. If they follow the schedule, instant payments reach the accounts holding most Canadian deposits.

2

Big Six stay off RTR past 2027, system remains fintech-only

Possible Resolves by End of 2027

Discussed by: Daniel Eberhard of KOHO, Hanna Zaidi of Wealthsimple

Critics said the system would be largely performative without the big banks. If incumbents keep using existing rails, RTR's reach stays limited to the eight launch members and later fintechs, and most Canadians see no change.

3

RTR connects to international instant-payment networks

Unlikely Resolves by End of 2028

Discussed by: Payments Canada officials, as reported by Ground News

Officials aim to eventually connect the RTR with global networks, including the European Union's. That would require cross-border standards and agreements well beyond the domestic launch.

Historical Context

3 moments from history that rhyme with this story — and how they unfolded.

May 2008

UK Faster Payments Service (2008)

The UK launched Faster Payments in May 2008, replacing a system where transfers could take up to three working days. It started with a limited set of banks and building societies, then expanded.

Then

Early coverage was partial, and some institutions joined months later.

Now

Faster Payments became the backbone of UK retail banking and now handles billions of transactions a year.

Why this matters now

Shows how a real-time rail starts narrow and becomes near-universal only as institutions migrate onto it.

February 2018

Australia's New Payments Platform (2018)

Australia's NPP launched in February 2018 with a small group of founding participants. The big four banks and others connected over the following months.

Then

Adoption grew as more institutions connected and the PayID addressing system spread.

Now

The NPP became the base layer for Australian instant transfers and account-to-account payments.

Why this matters now

A phased start with major banks arriving later mirrors Canada's rollout and its coverage gap.

July 2023

US FedNow (2023)

The Federal Reserve launched FedNow in July 2023 as a voluntary instant-payment service. Early participants were a mix of small banks and payment processors; large banks joined gradually.

Then

Coverage was uneven, and many large institutions stayed on the sidelines.

Now

Adoption has been slower than in countries that mandated participation.

Why this matters now

Shows that a voluntary, phased instant-payment system can leave coverage patchy for years.

Sources

(8)