Pull to refresh
Logo
China's factory activity returns to expansion in September

China's factory activity returns to expansion in September

Money Moves

Manufacturing PMI ends two-month contraction as AI-driven exports and fresh stimulus support output, while domestic demand lags

Yesterday: First-home buyer subsidies take effect

Overview

Updated 1 hour ago

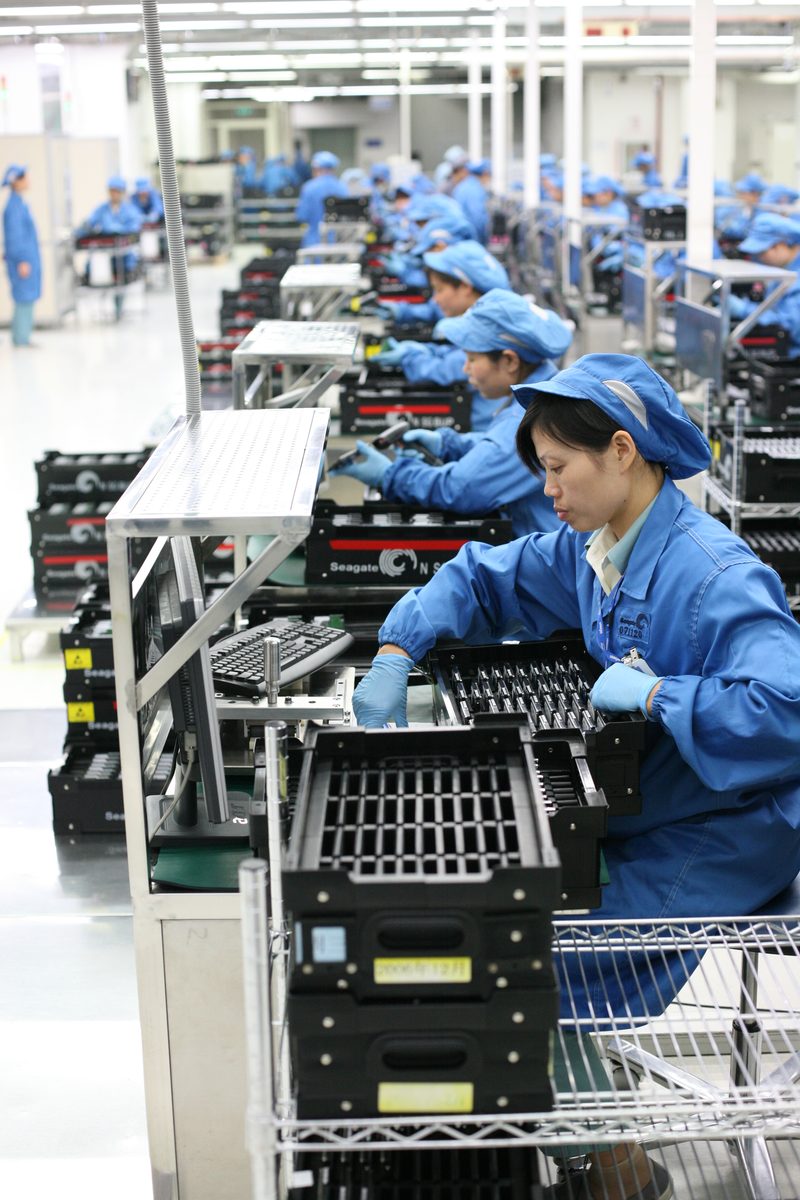
China's factory activity expanded in September for the first time in three months. The official purchasing managers' index (PMI) climbed to 50.1 from 49.8 in August, crossing the line that separates growth from contraction.

The rebound followed easing weather disruptions and strong global demand for AI-related hardware, which lifted exports. But domestic consumption and investment remain weak, and a prolonged property downturn continues to weigh on the broader economy. Beijing has rolled out new stimulus in response.

Why it matters

China's factory pulse moves commodity prices, shipping rates, and global supply chains — a sustained recovery steadies markets, a relapse shakes them.

Questions about this story

Free account needed to ask — your question is kept and asked for you right after sign-up. Answers are public.

No questions yet — be the first to ask.

Key Indicators

50.1
Manufacturing PMI, September 2026
Index where 50 separates expansion from contraction; returned to growth after two contraction months.
51.7
Production sub-index
Output gauge, up 1.3 points from August and the highest reading of 2026.
50.2
Non-manufacturing business activity
Services and construction index, back above 50 after rising 1.2 points.
60.8
Raw material purchase price index
Five-month high, driven by rising energy and commodity prices.

Voices

Curated perspectives — historical figures and your fellow readers.

Ever wondered what historical figures would say about today's headlines?

Sign up to generate historical perspectives on this story.

People Involved

Organizations Involved

Timeline

September 2026 October 2026

4 events Latest: Yesterday
Tap a bar to jump to that date
  1. First-home buyer subsidies take effect

    Latest Policy

    Interest subsidies begin for eligible buyers, one annualized point on up to 1 million yuan loans.

  2. Manufacturing PMI returns to expansion

    Economic Data

    NBS reports PMI at 50.1, ending two consecutive months of contraction.

  3. NDRC allocates final trade-in bonds

    Policy

    Agency releases last 62.5 billion yuan of ultra-long treasury bonds for consumer trade-in programs.

  4. PBOC eases monetary policy

    Policy

    Central bank cuts PSL rate to 1.5% and expands relending for tech and small businesses.

Scenarios

1

Steady expansion through year-end

Likely Resolves by End of 2026

Discussed by: Wen Tao at China Logistics Information Center; official forecasts

Manufacturing PMI stays at or above 50 through October, November, and December as infrastructure investment accelerates and trade-in programs lift consumer spending. Government-linked analysts point to about 2 trillion yuan of planned central state-owned enterprise infrastructure investment as the main support.

2

Recovery stalls, renewed contraction

Possible Resolves by Nov 30, 2026

Discussed by: Lynn Song at ING Bank; Reuters analysts

Weak domestic consumption, sluggish investment, and the property downturn pull the PMI back below 50 in October or November. ING's Lynn Song notes the recovery has been driven mostly by external demand and could fade if trade frictions or geopolitical uncertainty hit exports.

3

Stimulus accelerates growth

Possible Resolves by Jan 20, 2027

Discussed by: PBOC, NDRC, Ministry of Finance announcements

Additional policy measures, including housing loan subsidies and expanded relending, push manufacturing PMI above 51 and lift fourth-quarter GDP growth toward the top of Beijing's 4.5% to 5% target range. Infrastructure investment from central state-owned enterprises plays a major role in the pickup.

Historical Context

2 moments from history that rhyme with this story — and how they unfolded.

November 2008 – 2009

Global financial crisis stimulus (2008-2009)

With exports collapsing as the global financial crisis deepened, Beijing announced a 4 trillion yuan stimulus package in November 2008. The bulk went into infrastructure, housing, and rural development, with local governments and state banks financing the spending.

Then

Within a year, China's growth returned to double digits and manufacturing surged, pulling global commodity prices back up.

Now

The debt buildup and overcapacity left by the stimulus shaped China's economy for years and contributed to structural imbalances policymakers still address today.

Why this matters now

Shows Beijing's capacity to engineer a manufacturing recovery through massive state-led spending, the same lever implied by this year's planned infrastructure investment.

January – April 2023

Post-COVID reopening bounce (2023)

After China exited its COVID-zero policy in December 2022, factory activity rallied as supply chains unclogged and pent-up demand was released. The manufacturing PMI jumped above 52 within two months.

Then

The bounce faded within months as the property crisis and weak consumer confidence dragged the index back below the 50 line by spring.

Now

Became a cautionary example of an export-led rebound that fails to translate into durable domestic recovery.

Why this matters now

Demonstrates how quickly a Chinese factory PMI surge can fade when domestic structural problems persist, the key risk for the current recovery.

Sources

(11)